Shipping is entering a period of profound transformation driven by an increasingly stringent regulatory framework. Decarbonization is no longer a voluntary objective, but a compliance requirement shaped by a combination of global and European measures.
At the international level, the IMO Net-Zero Framework (NZF), approved at MEPC 83 in April 2025, would establish a trajectory towards net-zero emissions from shipping by or around 2050 and introduce greenhouse gas (GHG) fuel-intensity reduction requirements. Its formal adoption was postponed by one year in October 2025 [10].
At EU level, FuelEU Maritime covers ships above 5,000 gross tonnage calling at EU ports. The regulation progressively reduces the well-to-wake GHG intensity of energy used on board, requiring reductions from 2% in 2025 to 6% in 2030, 14.5% in 2035, 31% in 2040, 62% in 2045 and 80% by 2050 compared to a 2020 baseline. The regulation is scheduled for review by the end of 2027, with discussions expected on issues such as scope expansion, stricter targets and the possible inclusion of onboard carbon capture.
The EU Emissions Trading System (EU ETS) adds a further layer of pressure. Following its gradual phase-in from 2024, shipping companies face a 100% surrender obligation in respect of emissions from 1 January 2026. The system now covers not only CO₂ but also methane and nitrous oxide (N₂O), making it particularly relevant for LNG- and methane-fuelled vessels, whose methane emissions are therefore already priced rather than left outside the compliance perimeter. At the same time, carbon costs are expected to remain a significant factor as the ETS cap tightens over time. The ongoing review of the ETS is also considering new support mechanisms aimed at accelerating the uptake of sustainable maritime fuels (SMFs).
Taken together, the IMO NZF, FuelEU Maritime and the EU ETS will generate a growing demand for low- and zero-emission marine fuels [1]. This emerging demand creates a significant opportunity for SMFs broadly, and for e-LNG in particular, as shipowners and fuel suppliers seek scalable and compliant pathways to meet decarbonization requirements.
SMF encompasses a broad range of fuels that can contribute to reducing GHG emissions from shipping, including advanced biofuels and biogas, RFNBOs, and low-carbon fuels that meet the applicable sustainability and lifecycle emissions requirements. In practice, the SMF category therefore covers both bio-based and synthetic renewable or low-carbon fuels used in maritime transport. Within this broader category, e-SMF refers specifically to the RFNBO-based sustainable maritime fuels, including e-LNG and other synthetic fuels produced from renewable hydrogen.
Under Article 2(36) of RED III, an RFNBO is a liquid or gaseous fuel whose energy content is derived from renewable sources other than biomass. To count as an RFNBO under EU law, it must also meet the renewable electricity sourcing rules and the GHG accounting methodology (with a minimum 70% emissions saving) set out in Delegated Regulations (EU) 2023/1184 and (EU) 2023/1185. The definition turns on the production route and the lifecycle emissions performance of the fuel, not on the molecule that results from it. e-NG produced from renewable hydrogen and qualifying CO₂ therefore falls squarely within it, in exactly the same way as e-methanol, e-ammonia or e-diesel. Neither RED III, nor FuelEU Maritime, nor the Sustainable Transport Investment Plan restricts the e-SMF category to a sub-set of RFNBO pathways. A narrower reading may be a legitimate policy preference, but it is not a classification that can be derived from EU law.
e-LNG is produced by combining renewable hydrogen generated through electrolysis with captured CO₂ from sources that qualify under the RFNBO rules, including biogenic CO₂ and direct air capture, through a methanation process. The resulting synthetic methane, also referred to as e-methane or e-NG is then liquefied to produce e-LNG. As e-LNG is chemically identical to conventional LNG and bio-LNG, it can be used in existing LNG engines, vessels, storage facilities and bunkering infrastructure without requiring major modifications. Alongside bio-LNG, it offers a scalable route to decarbonizing LNG-powered vessels while leveraging existing maritime infrastructure and fuel supply chains.
The EU Sustainable Transport Investment Plan highlighted the role of e-SMFs in meeting FuelEU Maritime targets and identified methane-based pathways, including “LNG, bio-methane and future e-methane”, as options for the decarbonization of ocean-going shipping. The Commission's own framing therefore already places renewable methane among the pathways expected to contribute to the FuelEU Maritime targets.
Conventional oil-based drop-in maritime fuels alone cannot meet long-term decarbonization objectives. Achieving long-term climate objectives will therefore require a combination of sustainable drop-in fuels and alternative fuels.
Alternative-fuel vessels are vessels equipped to operate on fuels other than conventional drop-in marine fuels, including LNG, methanol, LPG, ammonia and hydrogen. These fuels generally require dedicated newbuilds or retrofits to accommodate different fuel storage, handling and safety requirements. At the same time, sustainable and low-emissions drop-in fuels can continue to play an important complementary role, including as pilot fuels required for the ignition of certain alternative fuels [14].
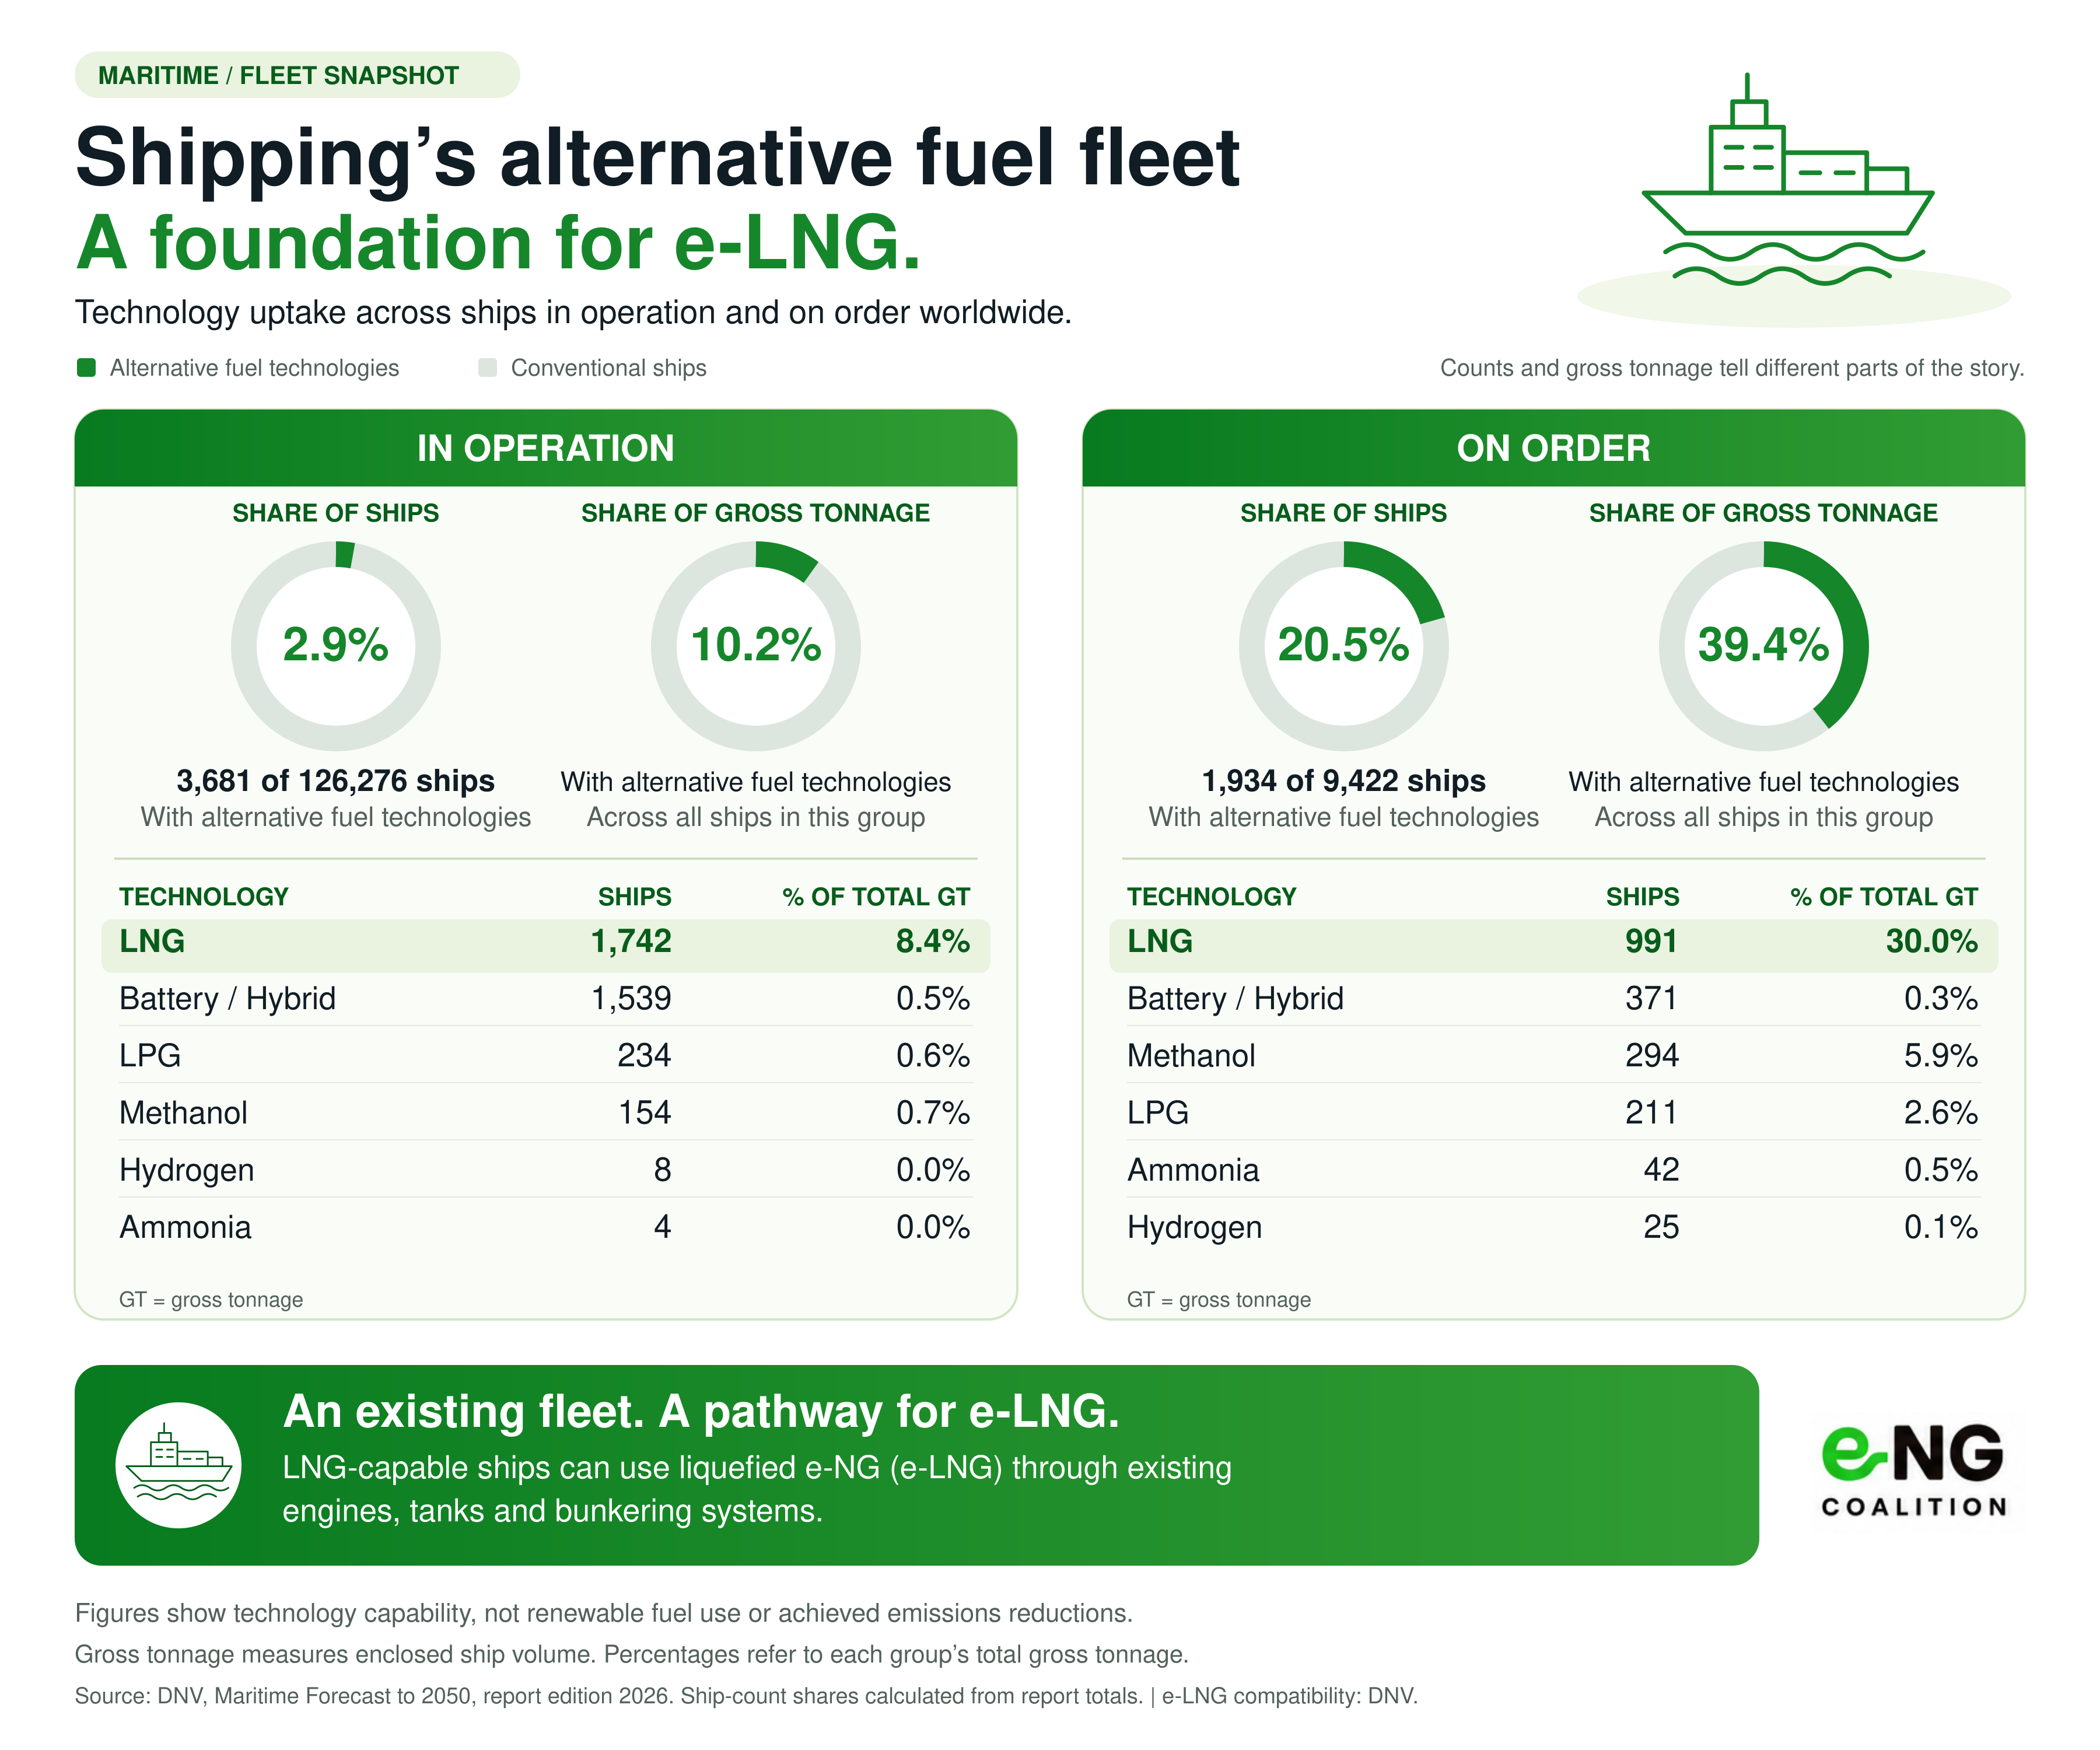
The uptake of alternative-fuel vessel technologies provides an important indication of which fuel pathways shipowners are selecting for the decades ahead. According to DNV’s Maritime Forecast to 2050, LNG is the dominant alternative fuel technology in global shipping. As of August 2026, 1,742 LNG-capable vessels were in operation, comprising 813 LNG carriers and 929 other LNG-fuelled vessels such as containerships, car carriers, tankers and cruise ships. By comparison, only 154 methanol-capable vessels, 234 LPG-capable vessels, 8 hydrogen-capable vessels, and 4 ammonia-capable vessels were in operation [3].
LNG also leads the global orderbook. As of August 2026, 991 LNG-capable vessels were on order, including 672 non-carrier vessels and 319 LNG carriers. This compares with 294 methanol-capable vessels, 211 LPG-capable vessels, 42 ammonia-capable vessels, and 25 hydrogen-capable vessels on order. LNG therefore represents the largest alternative-fuel segment both in the existing fleet and the future orderbook [3].
Considering only vessels capable of switching fuel type (LNG, methanol, LPG, ammonia and hydrogen, and excluding battery/hybrid propulsion, which does not represent a fuel switch), LNG accounts for 1,742 of the 2,142 fuel-switching-capable vessels currently in operation (81.3%) and 991 of the 1,563 such vessels on order (63.4%) [3].
In gross tonnage terms, LNG is even more dominant, representing 8.4% of the global fleet's gross tonnage and 30.0% of the global orderbook gross tonnage, compared with 0.7% and 5.9% for methanol, 0.6% and 2.6% for LPG, 0.0% and 0.5% for ammonia, and 0.0% and 0.1% for hydrogen, respectively. Excluding battery/hybrid propulsion, alternative fuel-switching technologies account for 9.7% of the global fleet's gross tonnage and 39.1% of the orderbook's gross tonnage – of which LNG represents 86.6% and 76.7%, respectively [3].
These findings are consistent with analyses from both Lloyd’s Register and Clarksons Research, which likewise identify LNG as the leading alternative fuel technology in both the existing fleet and the orderbook, significantly ahead of methanol, ammonia, hydrogen and other alternative fuel options [2, 10].
This trend matters because ships are long-lived assets. The LNG-capable vessels currently on the orderbook are likely to enter into service over the next few years [12], and these vessels could remain in service for at least 20 to 25 years. The LNG-fueled fleet currently being built will therefore remain operational well into the 2040s and 2050s, precisely when FuelEU Maritime requirements, the IMO NZF and other GHG reduction measures are expected to become more stringent.
The orderbook already confirms that thousands of LNG vessels will remain part of the global fleet for decades. The key question is therefore not whether LNG-fueled ships will still be sailing in 2040, but what fuel they will be using.
This is where e-LNG and bio-LNG become critical. Unlike other decarbonization pathways that may require major vessel retrofits, fuel-system replacements or premature asset retirement, e-LNG and bio-LNG can be used in existing LNG-fueled vessels and infrastructure without modification. As regulatory requirements tighten, these fuels provide a pathway for the rapidly growing LNG-capable fleet to continue operating while substantially reducing lifecycle GHG emissions [4].
Unlike other alternative marine fuels that require new supply chains, dedicated bunkering systems and vessel modifications, e-LNG is directly compatible with infrastructure that already exists at scale. Because e-LNG is chemically identical to conventional LNG, it can be transported, stored, bunkered and used through the same terminals, storage tanks, bunker vessels and engines without modifications.
The global LNG infrastructure is continuing to expand, with regasification capacity reaching 1,113.5 Mtpa across 50 markets by the end of 2025, including 62.9 Mtpa added during the year and a further 229.3 Mtpa under construction [6]. LNG bunkering infrastructure has also grown significantly, supported by a fleet of ~60 LNG bunker vessels worldwide and a further ~40 vessels on order [5].
LNG infrastructure already supports growing volumes of bio-LNG and, in the future, it will support e-LNG. For instance, bio-LNG is already being supplied through the same infrastructure used for conventional LNG. In Rotterdam, bio-LNG bunkering volumes increased from 2,775 m³ in 2024 to 17,644 m³ in 2025, a six-fold increase achieved without the need for new dedicated storage, transport or bunkering systems [6].
This contrasts with several other alternative fuel pathways, where supporting infrastructure remains at a much earlier stage of development. For example, there are currently limited bunkering and storage facilities for methanol, ammonia bunkering infrastructure has yet to be established at commercial scale and the number of ports offering low-GHG ammonia bunkering remains extremely limited [3, 11, 13].
The significance of this existing LNG infrastructure base should not be overstated: infrastructure readiness does not automatically resolve questions relating to feedstock availability, production costs or long-term supply. However, it does mean that the transition to renewable methane fuels can leverage an established global value chain rather than requiring the deployment of an entirely new one [4, 6].
Beyond fleet compatibility and infrastructure reuse, several technical and operational characteristics inherent to LNG carry over directly to e-LNG, since the two are chemically identical once liquefied.
LNG (and by extension e-LNG) offers a higher volumetric energy density than the other main alternative fuel candidates for deep decarbonization, at 21.6 MJ/L. By comparison, methanol provides 15.7 MJ/L, liquid ammonia 13.1 MJ/L, and liquid hydrogen only 8.5 MJ/L [9]. As a result, significantly larger fuel tanks are required for methanol, ammonia and hydrogen to store the same amount of energy.
While its lower energy density than MGO and the insulated tanks needed to store it at -162°C mean that e-LNG/LNG needs ~1.8 times the storage volume of MGO, this number remains lower than for methanol (~2.4x), ammonia (~2.9x) or liquid hydrogen (~4.5x) [9]. As a result, e-LNG/LNG provides a more favorable range-to-storage ratio for deep-sea shipping, requiring less tank space and fewer bunkering stops.
LNG also benefits from decades of operational experience and a mature regulatory framework, including established class rules, the IMO IGF Code, and dedicated training requirements. While LNG remains a cryogenic and flammable fuel requiring specific safety measures, its risks are well understood and supported by extensive industry experience [4, 10, 12]. In contrast, ammonia faces significant toxicity concerns [8, 11], hydrogen presents challenges related to flammability and material compatibility [9], and methanol requires careful management of fire and corrosion risks [7]. As a result, LNG currently offers the most mature and well-developed safety framework among alternative marine fuels, an advantage that directly extends to e-LNG.
LNG engine and propulsion technology is already commercially proven across all major vessel segments, and these same engines can operate on e-LNG without modification. By contrast, ammonia engines and hydrogen fuel cells remain at an earlier stage of development, with fuel cell costs still significantly above conventional marine propulsion.
Methane slip, unburned methane escaping during combustion, is a real and well-documented challenge specific to methane-fueled engines. It occurs in the engine and not in fuel production, and applies equally to fossil LNG, bio-LNG and e-LNG. Slip performance varies by engine architecture: high-pressure two-stroke engines have lower slips, while low-pressure four-stroke and low-pressure two-stroke designs have higher slips, particularly at low engine loads [4].
It is, however, a known, quantified and actively managed problem with a clear improvement trajectory (e.g., newer low-pressure four-stroke designs demonstrably narrowing the slip gap with high-pressure two-stroke engines) [4]. Fleet renewal is reinforcing this trend: in the LNG-fueled orderbook (excluding LNG carriers), high-pressure two-stroke engines, which deliver slip in the range of 0.2 g/kWh, account for 78% of installed main engine power, compared with 48% in the existing fleet [10].
It is also, critically, a problem that is already internalized in the metrics that determine compliance (cf. column Cslip of Annex II of FuelEU Maritime and the Guidance on the FuelEU maritime regulation). FuelEU Maritime accounts for methane slip in the well-to-wake GHG intensity of the energy used on board, the EU ETS covers methane emissions from shipping from 2026, and the IMO NZF captures it within the lifecycle GHG fuel intensity. Where a well-to-wake carbon intensity (CI) is quoted for e-LNG, slip is therefore captured inside that figure under the applicable methodology, and not excluded from it. The ~8.6 gCO₂eq/MJ value cited for e-LNG in Section 4 below, for instance, already includes the FuelEU default slip factor of 0.2% for a high-pressure dual-fuel engine [10]. Methane slip is a reason to keep improving engine design and measurement; it is not a basis for placing e-NG outside the e-SMF category.
Unlike ammonia and hydrogen, which still face unresolved emissions and safety challenges, LNG benefits from a mature regulatory framework and extensive operational experience. Ammonia raises concerns around N₂O emissions and ammonia slip, while hydrogen combustion may generate nitrogen oxides (NOx), requiring mitigation technologies that remain at an earlier stage of development.
Under RED III, an RFNBO must achieve at least a 70% GHG emissions saving relative to the fossil comparator of 94 gCO₂eq/MJ, corresponding to a maximum lifecycle CI of 28.2 gCO₂eq/MJ. Because compliance value under both FuelEU Maritime and the EU ETS is directly linked to a fuel's CI, the emissions profile of renewable methane fuels is central to their regulatory and commercial value proposition.
e-LNG performs well beyond this requirement. Produced from renewable hydrogen and captured CO₂, it qualifies as an RFNBO and benefits from RFNBO-specific recognition across EU legislation, including the RFNBO targets for transport under RED III, the FuelEU Maritime RFNBO reward factor of 2 until the end of 2033, and the 2% RFNBO sub-target that FuelEU Maritime may trigger from 2034. In a high-pressure dual-fuel engine, with methane slip included, fossil LNG has a well-to-wake intensity of ~76 gCO₂eq/MJ, while e-LNG's intensity is ~8.6 gCO₂eq/MJ or even less. That represents an emissions reduction of more than 88% against fossil LNG and of ~91% against the RED III fossil comparator of 94 gCO₂eq/MJ, far beyond the 70% required [10, 15]. With low-pressure engines at today's conservative FuelEU default slip factors, e-LNG would still sit at roughly 15–22 gCO₂eq/MJ, around 76-82% below fossil LNG used in the same engine. Under the draft IMO NZF, e-LNG would also fall below the thresholds for zero- or near-zero (ZNZ) fuel rewards, set at 19 gCO₂eq/MJ until 2034 and 14 gCO₂eq/MJ from 2035, a point Lloyd's Register makes explicitly [10].
In addition to that, and as mentioned previously, e-LNG demonstrates that deep maritime decarbonization does not necessarily require entirely new fuel ecosystems. As a renewable methane pathway, it combines the emissions performance needed to meet RFNBO requirements with the operational advantages of the existing LNG value chain. Its main challenge is not vessel compatibility, infrastructure deployment or onboard technology, but scaling production and ensuring access to sufficient volumes of renewable hydrogen and sustainable CO₂ sources. While LNG technologies continue to face scrutiny regarding the methane slip, comparable challenges exist for other alternative fuels, including toxicity and ammonia slip for ammonia, or storage and infrastructure constraints for hydrogen. Differences in lifecycle intensity between RFNBO pathways are also small in absolute terms: on Lloyd's Register's FuelEU factors, e-LNG (~8.6 gCO₂eq/MJ), e-methanol (~7.5) and e-ammonia (~5.0, before tank-to-wake N₂O) sit within a few grams of one another, against 76–92 gCO₂eq/MJ for the fossil fuels they replace [10].
Regulatory coherence will be essential. To unlock the potential of e-LNG, policymakers should ensure that renewable methane pathways are recognized consistently across regulatory frameworks. This includes explicit and harmonized treatment of e-LNG under RED III, FuelEU Maritime, the EU ETS and the IMO NZF, avoiding gaps or conflicting incentives that undermine investment signals. The current review of the EU ETS, the upcoming review of FuelEU Maritime and the adoption and implementation of the IMO NZF should be coordinated to avoid double counting, double payment, or overlapping compliance burdens. Clear and harmonized chain-of-custody rules for renewable methane will be equally important to facilitate cross-border trade, market liquidity and investment certainty, including consistent treatment of mass balance and of book-and-claim arrangements where physical delivery of the molecule is not practicable.
At the same time, policymakers should support the scale-up of e-NG and e-LNG production through targeted measures that increase renewable hydrogen availability, secure sustainable carbon sources and reduce the cost gap for early projects.
The maritime energy transition requires a technology-neutral approach without excluding viable renewable fuels from the conversation. No single fuel pathway will meet all operational needs, vessel types, or trade routes. Renewable fuels that deliver credible lifecycle emissions reductions and meet sustainability requirements should therefore be assessed on equal terms. In that context, e-LNG represents one of several viable pathways that can contribute to the transition. Its compatibility with existing vessels, infrastructure and established safety frameworks gives it a credible and practical role in maritime decarbonization. Excluding a compliant RFNBO pathway from the e-SMF label does not accelerate that transition. It narrows the set of options available to shipowners who are already subject to binding obligations, and it weakens the investment signal for fuels that are being produced today.
[1] ACER. 2026. Analysis of the European LNG market developments 2026 Monitoring Report. https://www.acer.europa.eu/sites/default/files/documents/Publications/ACER-LNG-Monitoring-Report-2026.pdf
[2] Clarksons Research. 2026. Tracking “Green” Technology Uptake. https://cyprusshippingnews.com/wp-content/uploads/2026/01/Green-Technology-Uptake-January-2026.pdf
[3] DNV. 2026. Maritime Forecast to 2050. https://www.dnv.com/maritime/maritime-forecast/
[4] DNV. 2026. Methane in shipping: LNG-fuelled ships and the switch to low-GHG methane. https://www.dnv.com/publications/methane-in-shipping/
[5] GIIGNL. 2026. GIIGNL Annual Report. https://giignl-documents.s3.fr-par.scw.cloud/public/ar-2026-annual-report.pdf
[6] IGU. 2026. World LNG Report 2026. https://www.datocms-assets.com/146580/1783403747-igu-world-lng-report-2026.pdf
[7] Lloyd’s Register. 2023. Fuel For Thought: Methanol. https://www.lr.org/en/knowledge/research/fuel-for-thought/methanol/
[8] Lloyd’s Register. 2024. Fuel For Thought: Ammonia. https://www.lr.org/en/knowledge/research-reports/2024/fuel-for-thought-ammonia-report/
[9] Lloyd’s Register. 2026. Fuel For Thought: Hydrogen. https://www.lr.org/en/knowledge/research-reports/2025/fuel-for-thought-hydrogen/
[10] Lloyd’s Register. 2026. Fuel For Thought: LNG. https://www.lr.org/en/knowledge/research-reports/2025/fuel-for-thought-lng-report/
[11] Mærsk Mc-Kinney Møller Center for Zero Carbon Shipping. 2026. E-ammonia │ Alternative maritime fuel information sheets. https://www.zerocarbonshipping.com/files/alternative-maritime-fuel-information-sheets-e-ammonia.pdf
[12] Mærsk Mc-Kinney Møller Center for Zero Carbon Shipping. 2026. E-methane │ Alternative maritime fuel information sheets. https://www.zerocarbonshipping.com/files/alternative-maritime-fuel-information-sheets-e-methane.pdf
[13] Mærsk Mc-Kinney Møller Center for Zero Carbon Shipping. 2026. E-methanol │ Alternative maritime fuel information sheets. https://www.zerocarbonshipping.com/files/alternative-maritime-fuel-information-sheets-e-methanol.pdf
[14] Mærsk Mc-Kinney Møller Center for Zero Carbon Shipping. 2026. Mapping the adoption process for new drop-in fuels. https://www.zerocarbonshipping.com/files/mapping-the-adoption-process-for-drop-ins.pdf
[15] World Economic Forum. (2026). Fuelling the Future: How Business, Finance and Policy can Accelerate the Clean Fuels Market. https://www.weforum.org/publications/fuelling-the-future-how-business-finance-and-policy-can-accelerate-the-clean-fuels-market/
------------------------------
For more information, contact Alexandra Popova at alexandra.popova@eng-coalition.org